
Macro Monthly: Resilient but uneven global growth
8 October 2026
Key takeaways
-
Disruption around the Strait of Hormuz continues to impact energy prices and the inflation outlook…
-
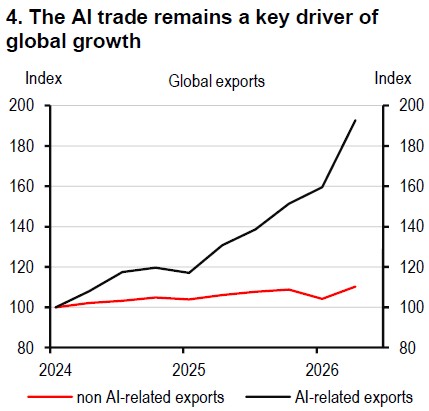
…but the AI cycle is playing a key role in keeping pockets of the global economy growing quickly…
-
…resulting in a ‘K-shaped’ economy that’s hard to interpret for policymakers
The global economy continues to perform better than expected, despite persistent risks. Ongoing conflicts, elevated debt levels, and the accelerating impact of AI are pulling the data in different directions and driving divergent economic outcomes across regions and sectors.
Prices remain contained
Core prices are yet to rise meaningfully
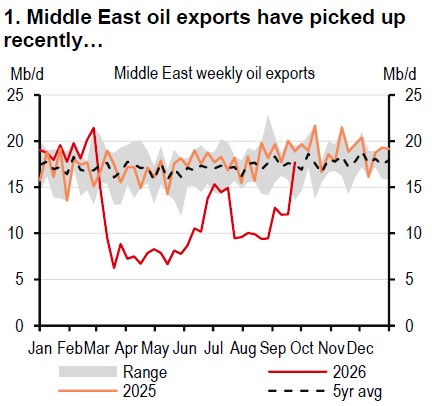
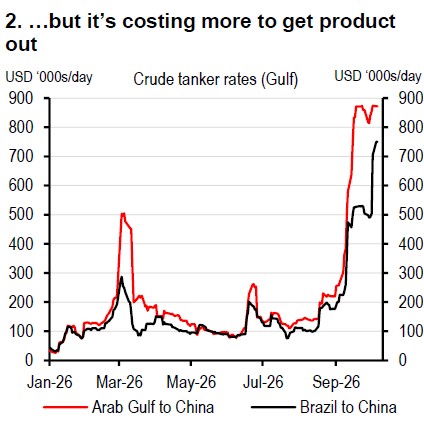
While flows of crude oil from the Middle East may be picking up, this is at a higher cost (Charts 1 and 2), and refined fuel prices and gas prices are a pressing inflationary concern. But there is still limited evidence of this spreading into core prices. Indeed, core inflation remains under control in the US and Europe, with rental costs accounting for a key part of the remaining stickiness in the US.
While the persistence of higher energy costs and the growing impact of El Niño on food prices poses upside inflation risks – weaker labour markets (partly due to the threats from AI), slower wage growth, and productivity improvements continue to keep broader inflation in check. Where costs are rising, firms are seemingly finding it hard to pass these on.
Rates moving higher
Bond yields are rising amid continued fiscal concerns
Nonetheless, more central banks are feeling that they can’t take too many chances and have either delivered rate rises or have signalled that they plan to (or do more). Rising policy rates haven’t helped bond market concerns over fiscal credibility in much of the world – and higher bond yields are posing an additional concern to indebted governments that face rising fiscal pressures from ageing populations.
Resilient growth
Year-to-date growth has largely beaten expectations
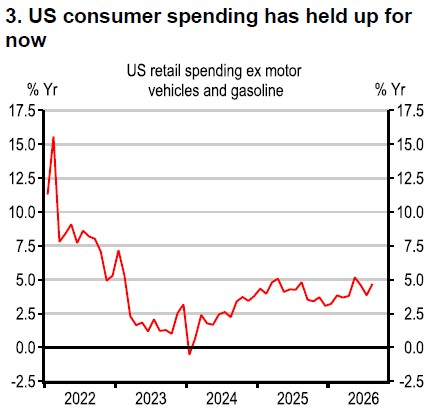
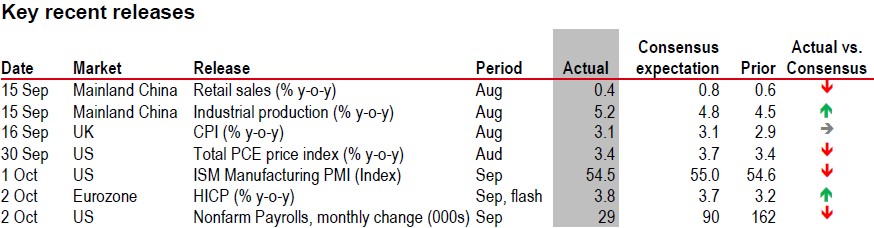
But despite all of this, the global economy continues to show remarkable resilience. The global composite PMI is at a 40-month high, consumer demand is holding up (Chart 3), and trade flows are being supported by the wave of AI-related shipments (Chart 4). Growth in the first three quarters of 2026 has outstripped expectations in most economies.
Challenges remain
Tighter fiscal policy and higher rates pose risks
While there are clearly challenges to this resilience in the coming months from squeezes to real incomes, tighter fiscal policy, and higher interest rates, the continued ability for the global economy to ride out these shocks remains encouraging, even if that growth is uneven and is not being felt by everyone.
Growth forecasts
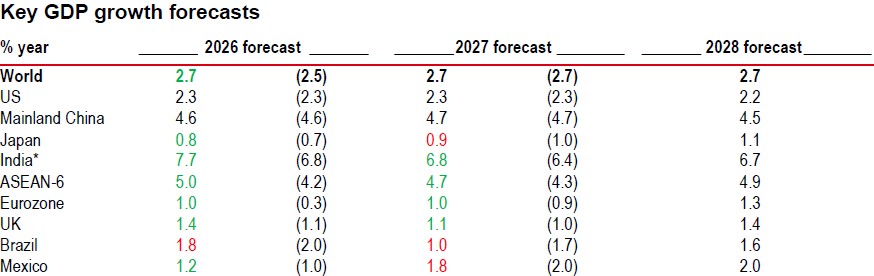
We forecast 2026 global GDP growth of 2.7%
With the exception of economies such as Korea and Taiwan, where we expect more active fiscal policy – fuelled by tech sector revenues – to support stronger domestic demand, we still forecast some moderation in global growth to the end of the year with higher inflation and higher interest rates weighing on consumer spending.
The upside surprises to Asian and European growth in 1H largely explains the upward revision to our annual average global GDP forecasts for 2026 from 2.5% to 2.7%. Our 2027 forecast is unchanged at 2.7%.
Share

Related Insights


Disclosure appendix
Important disclosures
This document is for information purposes only and it should not be regarded as an offer to sell or as a solicitation of an offer to buy the securities or other investment products mentioned in it and/or to participate in any trading strategy. Information in this document is general and should not be construed as personal advice, given it has been prepared without taking account of the objectives, financial situation or needs of any particular investor. Accordingly, investors should, before acting on it, consider the appropriateness of the information, having regard to their objectives, financial situation and needs. If necessary, seek professional investment and tax advice.
Certain investment products mentioned in this document may not be eligible for sale in some states or countries, and they may not be suitable for all types of investors. Investors should consult with their HSBC representative regarding the suitability of the investment products mentioned in this document and take into account their specific investment objectives, financial situation or particular needs before making a commitment to purchase investment products.
The value of and the income produced by the investment products mentioned in this document may fluctuate, so that an investor may get back less than originally invested. Certain high-volatility investments can be subject to sudden and large falls in value that could equal or exceed the amount invested. Value and income from investment products may be adversely affected by exchange rates, interest rates, or other factors. Past performance of a particular investment product is not indicative of future results.
HSBC and its affiliates will from time to time sell to and buy from customers the securities/instruments (including derivatives) of companies covered in HSBC Research on a principal or agency basis.
Whether, or in what time frame, an update of this analysis will be published is not determined in advance.
HSBC may use Artificial Intelligence (AI) tools approved for adoption within HSBC in the development of its research reports, utilizing these technologies to analyse large volumes of data, enhance efficiency and improve the overall user experience. This includes but is not limited to paraphrasing, developing suitable captions and supporting data visualisation. It is important to note that while AI tools assist in various aspects of report creation, all investment recommendations and opinions presented herein are formulated and approved exclusively by our research analysts. The final content of the report reflects the professional judgement and expertise of our research analysts, ensuring compliance with regulatory standards and maintaining the integrity of our research process.
Additional disclosures
1. This report is dated as at 07 October 2026.
2. All market data included in this report are dated as at close 06 October 2026, unless a different date and/or a specific time of day is indicated in the report.
3. HSBC has procedures in place to identify and manage any potential conflicts of interest that arise in connection with its Research business. HSBC's analysts and its other staff who are involved in the preparation and dissemination of Research operate and have a management reporting line independent of HSBC's Investment Banking business. Information Barrier procedures are in place between the Investment Banking, Principal Trading, and Research businesses to ensure that any confidential and/or price sensitive information is handled in an appropriate manner.
4. You are not permitted to use, for reference, any data in this document for the purpose of (i) determining the interest payable, or other sums due, under loan agreements or under other financial contracts or instruments, (ii) determining the price at which a financial instrument may be bought or sold or traded or redeemed, or the value of a financial instrument, and/or (iii) measuring the performance of a financial instrument or of an investment fund.
Disclaimer
This document is prepared by The Hongkong and Shanghai Banking Corporation Limited (‘HBAP’), 1 Queen’s Road Central, Hong Kong. HBAP is incorporated in Hong Kong and is part of the HSBC Group. This document is distributed by HSBC Continental Europe, HBAP, HSBC Bank (Singapore) Limited, HSBC Bank (Taiwan) Limited, HSBC Bank Malaysia Berhad (198401015221 (127776-V))/HSBC Amanah Malaysia Berhad (200801006421 (807705-X)), The Hongkong and Shanghai Banking Corporation Limited, India (HSBC India), HSBC Bank Middle East Limited, HSBC UK Bank plc, HSBC Bank plc, Jersey Branch, and HSBC Bank plc, Guernsey Branch, HSBC Private Bank (Suisse) SA, HSBC Private Bank (Suisse) SA DIFC Branch, , HSBC Financial Services (Lebanon) SAL, HSBC Private banking (Luxembourg) SA, and The Hongkong and Shanghai Banking Corporation Limited (collectively, the “Distributors”) to their respective clients. This document is for general circulation and information purposes only. This document is not prepared with any particular customers or purposes in mind and does not take into account any investment objectives, financial situation or personal circumstances or needs of any particular customer. HBAP has prepared this document based on publicly available information at the time of preparation from sources it believes to be reliable but it has not independently verified such information. The contents of this document are subject to change without notice. HBAP and the Distributors are not responsible for any loss, damage or other consequences of any kind that you may incur or suffer as a result of, arising from or relating to your use of or reliance on this document. HBAP and the Distributors give no guarantee, representation or warranty as to the accuracy, timeliness or completeness of this document. This document is not investment advice or recommendation nor is it intended to sell investments or services or solicit purchases or subscriptions for them. You should not use or rely on this document in making any investment decision. HBAP and the Distributors are not responsible for such use or reliance by you. You should consult your professional advisor in your jurisdiction if you have any questions regarding the contents of this document. You should not reproduce or further distribute the contents of this document to any person or entity, whether in whole or in part, for any purpose. This document may not be distributed to any jurisdiction where its distribution is unlawful.
The following statement is only applicable to HSBC Bank (Taiwan) Limited with regard to how the publication is distributed to its customers: HSBC Bank (Taiwan) Limited (“the Bank”) shall fulfill the fiduciary duty act as a reasonable person once in exercising offering/conducting ordinary care in offering trust services/business. However, the Bank disclaims any guaranty on the management or operation performance of the trust business.
The following statement is only applicable to by HSBC Bank Australia with regard to how the publication is distributed to its customers: This document is distributed by HSBC Bank Australia Limited ABN 48 006 434 162, AFSL/ACL 232595 (HBAU). HBAP has a Sydney Branch ARBN 117 925 970 AFSL 301737.The statements contained in this document are general in nature and do not constitute investment research or a recommendation, or a statement of opinion (financial product advice) to buy or sell investments. This document has not taken into account your personal objectives, financial situation and needs. Because of that, before acting on the document you should consider its appropriateness to you, with regard to your objectives, financial situation, and needs.
Important Information about the Hongkong and Shanghai Banking Corporation Limited, India (“HSBC India”)
HSBC India is a branch of The Hongkong and Shanghai Banking Corporation Limited. HSBC India is a distributor of mutual funds and referrer of investment products from third party entities registered and regulated in India. HSBC India does not distribute investment products to those persons who are either the citizens or residents of United States of America (USA), Canada, Australia or New Zealand or any other jurisdiction where such distribution would be contrary to law or regulation.
Singapore
In Singapore, this document:
• has not been reviewed by any regulatory authority in Singapore or any other jurisdiction.
• is issued by HSBC Bank (Singapore) Limited (the "Bank") in the conduct of its business in Singapore and is for general information.
• is only meant for the person who received it and should not be copied or shared with others, either fully or partially, for any reason.
• must not be sent to the United States, Canada or Australia or to any other jurisdiction where sharing it is illegal. If someone uses or copies this document or video without permission, they could face legal action.
• gives a broad overview of the current economic environment and is not meant to be investment research or advice or a recommendation to buy or sell investments. Some parts might talk about future events, but these are just predictions and not promises nor guarantees of future performance or events. Actual results might turn out differently due to various reasons. The Bank is not responsible for updating these predictions or explaining why actual results could differ from those predictions.
• does not create any contracts and isn’t meant as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction where it is not legal. Investments can increase or decrease in value, and you might not get back the amount you initially invested. Investments come with market risks, so it is important to read all investment-related documents carefully. The opinions shared are from the HSBC Global Investment Committee at the time of creating this document or video and reflect its global perspective, which might differ from local views of the Bank. These opinions can change anytime and might not match HSBC Asset Management‘s current portfolios’ composition. HSBC Asset Management manages individual portfolios based on each client’s objectives, risk preferences, time horizon, and market conditions.
• has not been created following legal requirements for independent investment research and is not subject to any prohibition on dealing ahead of its dissemination.
• is not meant to offer accounting, legal or tax advice. Before making any investment decision, consider consulting a financial adviser. If you decide not to seek advice, carefully assess if the investment product is suitable for you. It is recommended to obtain appropriate professional advice when needed.
Investing overseas can lead to changes in the value of your investments due to currency exchange rates, which may cause them to rise or fall. Emerging markets are riskier and more unpredictable compared to established markets. These economies often depend heavily on international trade and can be adversely impacted by trade barriers, currency controls, adjustments in currency values, the economic conditions of their trading partners and other protective measures imposed by those partners.
We are not responsible for the accuracy and/or completeness of any third-party information obtained from sources we believe to be reliable but have not independently verified.
Mainland China
In mainland China, this document is distributed by HSBC Bank (China) Company Limited (“HBCN”) to its customers for general reference only. This document is not, and is not intended to be, for the purpose of providing securities and futures investment advisory services or financial information services, or promoting or selling any wealth management product. This document provides all content and information solely on an "as-is/as-available" basis. You SHOULD consult your own professional adviser if you have any questions regarding this document.
The material contained in this document is for general information purposes only and does not constitute investment research or advice or a recommendation to buy or sell investments. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. HSBC India does not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. Investments are subject to market risk, read all investment related documents carefully.
Should you wish to use AI technology (computational, statistical, machine-learning or other artificial intelligence techniques to infer or learn from data to find patterns, take actions, make decisions, or generate output) to help you analyse, summarise or evaluate this publication and/or any other research materials provided to you by HSBC, you shall seek HSBC consent in advance of any such use and not upload this publication and/or any other research materials produced by HSBC to an AI system or otherwise use AI technology in connection with the research services HSBC provides to you without our consent.
© Copyright 2026. The Hongkong and Shanghai Banking Corporation Limited, ALL RIGHTS RESERVED. No part of this document may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording or otherwise, without the prior written permission of The Hongkong and Shanghai Banking Corporation Limited.
Important information on sustainable investing
“Sustainable investments” include investment approaches or instruments which consider environmental, social, governance and/or other sustainability factors (collectively, “sustainability”) to varying degrees. Certain instruments we include within this category may be in the process of changing to deliver sustainability outcomes.
There is no guarantee that sustainable investments will produce returns similar to those which don’t consider these factors. Sustainable investments may diverge from traditional market benchmarks. In addition, there is no standard definition of, or measurement criteria for sustainable investments, or the impact of sustainable investments (“sustainability impact”). Sustainable investment and sustainability impact measurement criteria are (a) highly subjective and (b) may vary significantly across and within sectors.
HSBC may rely on measurement criteria devised and/or reported by third party providers or issuers. HSBC does not always conduct its own specific due diligence in relation to measurement criteria. There is no guarantee: (a) that the nature of the sustainability impact or measurement criteria of an investment will be aligned with any particular investor’s sustainability goals; or (b) that the stated level or target level of sustainability impact will be achieved.
Sustainable investing is an evolving area and new regulations may come into effect which may affect how an investment is categorised or labelled. An investment which is considered to fulfil sustainable criteria today may not meet those criteria at some point in the future.